Last week, someone in a stock forum posted a comment requested for stocks in KLSE which break 52 weeks low. This is indeed a very popular rule, you might be able to get the list from newspaper or some other website. In this post, let's try to develop this scanner, it is only one line of code! Why not we create it ourselves?
The code is as below:
Filter = C < Ref(LLV(L, 260), -1);
That's it. C is close price, L is is low price. The function LLV is to find out lowest value of the bars in the period. The second parameter is period which is 260 days here. 260 days is number of working days in a years (deduct weekend). To make it simple we will not consider other market close days like public holiday. The value return from LLV(L, 260) is the lowest price in last 260 days (bars). Function Ref refers to previous one day of value of LLV(L, 260). If we read this line of code in plain English, it is - Get me list of stock where close price is lower than the lowest price in the previous period of 260 days from yesterday. This is exactly what we want - today price breaks the new low of previous 260 days.
In Amibroker, we will use "Explore" feature in analysis to run this code as custom formula, we will get 52 weeks low stocks list in just a few seconds.
The following is the screenshot of our 52 weeks low scanner Amibroker "Explore" result.
Note that, Amibroker also provide time frame related functions to compress daily bar to weekly bar so we can operate on weekly bars. I will let you guys to explore these functions if you are interested, you can post me a comment if you face any issue.
You can follow result of the 52 Weeks Low Scanner. I will update this result at least once per week.
Friday, June 30, 2017
Wednesday, June 21, 2017
Develop and Back Test a Breakout Strategy
It has a been a while I haven't updated this blog, I was busy working on my trading algorithm and I started running one of my trading strategy live for few months now! Best of all, I managed to create a trading management platform which help me to manage my order including submission of buy/sell order. That means, my trading system is fully automated and it can run unattended without any human intervention. It could be the first fully automated trading system running by retail investor in KLSE! Sound interesting? Stay tuned, I might show you how it works in next posts.
Nonetheless, I am still working hard on R&D of more new trading strategies. I would like to have at least 2 trading strategies running live concurrently to diversify.
Recently I received a set of trading rules from a friend. I have created Amibroker program from the rules. In this post, I will show you guys how to convert this rules to code and back test it. As I am a strong believer of data and statistic, whether these rules work or not, I will let back test result speaks for itself.
The trading rules go as following:
1. Price breakout from side way with huge volume
2. Golden cross before the price break out - Short MA crosses above long MA
3. Wait for pullback with small volume after the breakout
4. After pullback enter at next day open if current close price is greater than previous day high
5. Set the cut loss point to previous day low
6. Sell at next day open if any of the condition met
- price hit cut loss point
- death cross - short MA cross below short MA
- price drop with huge volume
- price open high close low with high volume
- price hits trailing stop
7. Note that the rule only applicable for stock with price from 0.2 to 1.5
At a glance, these are quite common and typical rules for a breakout or momentum strategy, I did apply some of the rules in some of my previous trading strategies and they work very well. But will all these rule work as a complete trading system or strategy? Let's find out.
Let's examine the rule one by one and I will show you how do I quantify it and convert it to Amibroker code.
Rule 1. Price breakout from side way with huge volume
Code explanation:
//sideway
sideway = Sum(RSI(14) > 65 OR RSI(14) < 35, 40) < 5 AND ROC(C, 40) < 15 AND ROC(C, 40) > -15;
Explanation: The line of code expresses price moving in side way for last 40 days. It seems a bit complex, but the idea of side way is price should not fluctuate too much and the different of today price with previous 40th days must be small, in the code it is within -15% and 15%. I uses RSI to indicate price should not fluctuate too much, RSI value should be mostly within 35 and 65 in 40 days period. The rules doesn't say how long is the period of side way, but here I have hard coded to 40 days. We could optimize this value in back testing later.
//breakout
breakout = C > Ref(HHV(H, 40), -1);
Explanation: The line of code above verifies the closing price today is greater than the highest price of previous 40 days. In another words, the price has breakout from 40 days highest price. Again we can leave 40 days as a parameter to optimize.
//decent volume
decentVolume = MA(V, 3) > MA(V, 18);
Explanation: 3 period moving average of volume of the stock is greater than 18 period of moving average of volume. It means the recent volume is relatively big.
Rule 2. Golden cross before the price break out - Short MA crosses above long MA
//short MAA stay above Long MA
shortMAAboveLongMA = MA(C, 20) >= MA(C, 60);
Explanation: I simplify the rule by short MA must stay above long MA.
Rule 3. Wait for pullback with small volume after the breakout
tradeFilter = volumeFilter AND priceFilter;
monitorSignal = breakout AND decentVolume AND shortMAAboveLongMA AND Ref(sideway, -3) AND tradeFilter;
//Average volume around breakout period
averageBreakoutPeriodVolume = ValueWhen(monitorSignal, MA(V, 5));
//price drop with small volume
priceDropWithSmallVolume = C < Ref(C, -1) AND V <= averageBreakoutPeriodVolume;
fisrtAdjustAction = priceDropWithSmallVolume AND Ref(allUpSinceSignal, -1);
//adjust
allAdjustSinceFirstAdjust = priceDropWithSmallVolume AND BarsSince(fisrtAdjustAction) == Sum(priceDropWithSmallVolume, BarsSince(fisrtAdjustAction)) AND BarsSince(fisrtAdjustAction) <= 5;
Explanation: The codes above are not easy to understand especially for beginner. The first 2 lines however are not related to pullback, it just combines all of the conditions above so that we can pass the variable to our code about pullback. The third line is to get the average volume when the price breakout from side way. The second line is to define the pullback action where the price should drop and volume should be smaller than average volume when breakout. The last 2 lines express one or more than one pullback action on each bar until the current bar. For example, if price pullbacks from Monday to Wednesday, then stock price must drop everyday with small volume (compare to breakout volume) for every single days in this period.
Rule 4. After pullback enter at next day open if current close price is greater than previous day high
//entry bar
entrySignal = C > Ref(H, -1) AND Ref(allAdjustSinceFirstAdjust, -1);
//Buy Signal
Buy = entrySignal;
Explanation: This is our actual entry signal. It compares today close price with previous high price, if close price is higher than yesterday highest price, it is an indication that pullback is over and stock price is reversed. We set the entry signal as our buy signal. Based on backtest setting, we will buy this stock at next day open price.
So far we have completed our Buy rules. Let;s continue working on Sell rules below.
Rules 5. Set the cut loss point to previous day low
cutLossPoint = ValueWhen(entrySignal, Ref(L, -1));
Explanation: This is a simple formula, we just get the lowest price of the bar when entry signal is triggered and set it as our cut loss point.
Rule 6. Sell at next day open if any of the condition met
- price hit cut loss point
- death cross - short MA cross below short MA
- price drop with huge volume
- price open high close low with high volume
deathCross = Cross(MA(C, 60), MA(C, 20));
//bad Volume
badVolume = V > MA(V, 5) * 2 OR V > averageBreakoutPeriodVolume;
//Drop with bad volume
badDrop = C < Ref(C, -1) AND C < O AND badVolume;
//Open Up Close Low with bad volume
openUpCloseLow = O > Ref(C, -1) AND C < O AND (C-L)/(H-L) < 0.5 AND badVolume;
Sell = C < cutLossPoint OR deathCross OR badDrop OR openUpCloseLow;
Explanation: The code above should be self explanatory. The badVolume variable refers to high volume when share price drop. I define it as volume of the bar greater than 2 times of 5 days moving average of volume or the volume is greater than the average volume when breakout. So if share price drop or share price open high and close low with with "bad" volume it will meet our sell condition. Similarly, we will sell the stock at next day market open.
Rule 7. Note that the rule only applicable for stock with price from 0.2 to 1.5 & volume filter
//price filter
priceFilter = C > 0.2 AND C < 1.5;
//decent volume to trade
volumeFilter = (MA(V, 20) * C) > 3500;
//monitor signal
tradeFilter = volumeFilter AND priceFilter;
Explanation: Again, a self explanatory code, we only buy stock which close price is between 0.2 to 1.5. We also have to make sure the volume of stock is liquid enough for us to trade. We simply check it by price volume value of the stock is greater than 3500 (or RM 350000 since in KLSE the volume is in lot - 100 shares). If you notice the code in Rule 3 above, the condition is applied by Anded with other rules.
That's all about the important part of my code for the breakout strategy, I have omitted some other codes like position sizing. I set the position size to maximum 5 positions with equal 20% of capital each.
Back test Result
Let jump to the back test result and examine a few of our sample trades.
The back test period is from 1-1-2001 to 31-12-2016 which cover 16 years of historical data for all stocks listed on KLSE. First image is statistic of backtest. It shows the performance summary with 7.89% annual return and 20.28% average draw down. The second image is equity curve and draw down chart.
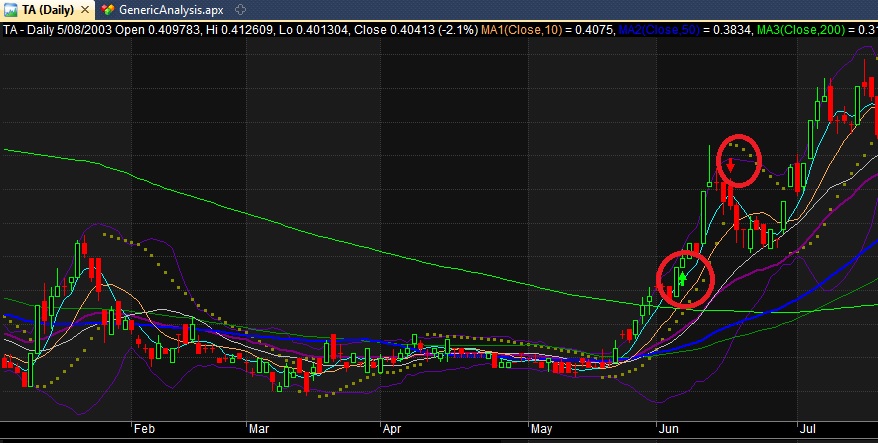
The chart above shows a typical winning trade, green and red arrows are entry and exit respectively. You can refer to the rules explained above to learn how the signal are generated.
The chart above shows a typical lossing trade.
In conclusion, this post focuses on converting the rules of a strategy to code, back test and verify whether it meet our expectation. I will not touch on how to optimize the rule and to improve a strategy here. I always advise traders to backtest a strategy and verify any trading idea/rule before following it. Some of the rules seems to be working or it could be given by some successful sifu which looks convincing, but the result from backtesting could reveal another story. Back testing definitely will help to eliminate or reduce the risk in this respect.
Thursday, May 21, 2015
KLSE Share Trading Signal - Volume Spike Strategy
The following are the trade signals generated from Volume Spike Strategy System. The date above each table is the date of trading day to trade the signals.
Entry Rules - Buy Signal
03/08/2015
Entry Rules - Buy Signal
- Check the stock price within 30 minutes before market close, buy at market price if price is up from previous day close (green) and only up for less than 10%. Don't buy if the conditions are not met.
Exit Rules - Sell Signal
- Sell when market open at market price
03/08/2015
| Counter | Close Price | Trade Signal | Spike Volume | 200 Days Average Volume | RSI(9) |
|---|---|---|---|---|---|
Disclaimers: The signals are provided for educational purpose only. Trade at your own risk. KLSE System Trader will not responsible for any financial loss trading the signals above.
Saturday, May 2, 2015
Performance result of a share trading system
In my previous post, I have explained about back testing process. But how do we determine whether performance result of a back testing is good? Is annual return the only statistic which we should consider? Apparently, the answer is no.
The following are the summary of statistics which we should consider:
The following are the statistics from back testing of volume spike strategy, the statistics explained above are highlighted in RED
The following are the summary of statistics which we should consider:
- Annual return - No doubt that annual return is a most well known statistic which most of the traders will look at. Generally, 20-40% is a decent return for a trading system.
- Average bars held - Average number of days a stock is held. It depends on your strategy whether it is a short, medium or long term strategy. Average bars held could be range from 1-5 (days) for short term trading strategy, few days to few months for mid term strategy and few weeks to months or years for long term strategy.
- Winning rate - Wining rate is how many percent of the trades are profitable out of total trades. High winning rate is important but we also need to consider average profit for a winning trade. For example, the winning rate for system A is 60% but the average profit for a winning trade is only 1%. This system is not better than system B which has 40% winning rate and 10% average profit for a winning trade.
- Maximum consecutive win - The largest number of consecutive win trades. The higher is the better. But we have to compare this statistic with maximum consecutive lose. Ideally maximum consecutive win should be greater than maximum consecutive loss. However it depends on our strategy, for example trend following strategy with lower winning rate tend to have higher maximum consecutive loss.
- Maximum consecutive lose - The largest number of consecutive lose trades. Ideally, this number should not be too high. High maximum consecutive lose will affect our confident on a trading system. If our system are having more than 15 consecutive loss trades in live trading, most likely we will lost confident and eventually abandon the system.
- Maximum trade drawdown - In simple words, maximum trade drawndown refer the loss of worst performing trade in the back testing.
- Maximum system drawdown - System drawdown refers to percentage of equity dropping from its high. For instance, a back testing cover 10 years period from 2001 to 2010. The starting capital is $100,000, in May, 2005 the total equity is $500,000. But due to bear market, there were high number of consecutive lose trades and in August 2005, the equity was dropping to $400,000 before rising again. The drawdown can be calculated as (500000-400000)/500000 * 100 = 20%.
- CAR/MaxDD - The value is derived from dividing annual return by maximum system drawdown. This is one the of most the important statistic to determine the performance of a trading system. CAR/MaxDD should be 1 or greater than 1.
The following are the statistics from back testing of volume spike strategy, the statistics explained above are highlighted in RED
| Statistics |
|---|
| All trades | Long trades | Short trades | |
|---|---|---|---|
| Initial capital | 100000.00 | 100000.00 | 100000.00 |
| Ending capital | 5175603.43 | 5175603.43 | 100000.00 |
| Net Profit | 5075603.43 | 5075603.43 | 0.00 |
| Net Profit % | 5075.60 % | 5075.60 % | 0.00 % |
| Exposure % | 55.51 % | 55.51 % | 0.00 % |
| Net Risk Adjusted Return % | 9143.22 % | 9143.22 % | N/A |
| Annual Return % | 30.09 % | 30.09 % | 0.00 % |
| Risk Adjusted Return % | 54.20 % | 54.20 % | N/A |
| Total transaction costs | 411330.66 | 411330.66 | 0.00 |
| All trades | 807 | 807 (100.00 %) | 0 (0.00 %) |
| Avg. Profit/Loss | 6289.47 | 6289.47 | N/A |
| Avg. Profit/Loss % | 5.80 % | 5.80 % | N/A |
| Avg. Bars Held | 26.14 | 26.14 | N/A |
| Winners | 316 (39.16 %) | 316 (39.16 %) | 0 (0.00 %) |
| Total Profit | 8290827.88 | 8290827.88 | 0.00 |
| Avg. Profit | 26236.80 | 26236.80 | N/A |
| Avg. Profit % | 24.80 % | 24.80 % | N/A |
| Avg. Bars Held | 42.64 | 42.64 | N/A |
| Max. Consecutive | 10 | 10 | 0 |
| Largest win | 1131384.57 | 1131384.57 | 0.00 |
| # bars in largest win | 197 | 197 | 0 |
| Losers | 491 (60.84 %) | 491 (60.84 %) | 0 (0.00 %) |
| Total Loss | -3215224.46 | -3215224.46 | 0.00 |
| Avg. Loss | -6548.32 | -6548.32 | N/A |
| Avg. Loss % | -6.42 % | -6.42 % | N/A |
| Avg. Bars Held | 15.53 | 15.53 | N/A |
| Max. Consecutive | 12 | 12 | 0 |
| Largest loss | -80543.62 | -80543.62 | 0.00 |
| # bars in largest loss | 34 | 34 | 0 |
| Max. trade drawdown | -555393.67 | -555393.67 | 0.00 |
| Max. trade % drawdown | -31.30 % | -31.30 % | 0.00 % |
| Max. system drawdown | -629463.10 | -629463.10 | 0.00 |
| Max. system % drawdown | -20.45 % | -20.45 % | 0.00 % |
| Recovery Factor | 8.06 | 8.06 | N/A |
| CAR/MaxDD | 1.47 | 1.47 | N/A |
| RAR/MaxDD | 2.65 | 2.65 | N/A |
| Profit Factor | 2.58 | 2.58 | N/A |
| Payoff Ratio | 4.01 | 4.01 | N/A |
| Standard Error | 726223.99 | 726223.99 | 0.00 |
| Risk-Reward Ratio | 0.26 | 0.26 | N/A |
| Ulcer Index | 10.50 | 10.50 | 0.00 |
| Ulcer Performance Index | 2.35 | 2.35 | N/A |
| Sharpe Ratio of trades | 0.47 | 0.47 | 0.00 |
| K-Ratio | 0.0181 | 0.0181 | N/A |
Sunday, April 26, 2015
Share Trading System Development - Back Testing
This is the subsequent post about process of share trading system development. Similarly I will use volume spike strategy which I outlined in my previous post as an example.
Implementing your strategy as code(custom formula) in Amibroker is not complicated but how could we verify that our strategy is actually working and profitable? The answer is you have to test your strategy against historical data. There are many providers which you can get KLSE end of day (EOD) historical data from. You should make sure the data is adjusted for bonus, split, consolidate and special large dividend.
The process of testing your strategy against historical data is called back testing. From the testing you could fine tune your code and parameters to improve the performance of the system. This is called optimization. However, over optimization will cause your system to only perform well on the data which you have tested against with. This is because the data is static and you optimize your code to fit the data. This issue is called curve fitting. Most probably in live trading, your system will not perform well as the result from your back testing. The solve this issue I will split my data to in sample data and out of sample data. The concept is simple, you do the back testing optimization against one set of data (in sample data) and then verify the performance of your system by testing against another set of data (out of sample data). You have done the right optimization if the performance of your system is consistent for in sample and out of sample data. The process of optimizing your system against in sample data and verify its result against out of sample data is also known as walk forward analysis. Amibroker support optimization and walk forward analysis out of the box.
Now I will use my strategy to explain about the back testing process above so that you could have better idea. Assuming you have implemented the volume spike strategy as I outlined in previous post and you have 20 years historical EOD data imported to Amibroker. Let us refer back to the setup of volume spike strategy, in the step to identify volume spike, we have parameter n as how many time the spike volume is greater than average volume. Assuming we set this parameter to 1.5 initially. Before back testing, we split our historical EOD as below:
Note that this is just a simplified example to explain the concept, in real back testing, we could split EOD to multiple sets of in sample and out of sample data.
Now, we can start testing our system against in sample data. Let us assume we only focus on annual return for now as performance indicator of your trading system (I will explain later about what aspects we should look at to determine the performance of a system in my next post, apparently, annual return should not be the only consideration). After back testing, we found that the annual return is 15% which we are not happy with. We should do another back test against out of sample data as a benchmark too, assuming that the annual return which we get is consistent which is also around 15%.
Now we will try to optimize this parameter by trying different value, let us say when we set this value to 5 and we notice that the back test result has been improved to 25% which meets our expectation. Then, we will need to verify our optimization result against out of sample data. For instance, the annual profit from back test against out of sample data is 16%. Obviously, the result is far behind our expectation, hence we haven't identified the optimum parameter. We should go back to optimized the parameter again and repeat the step of optimizing against in sample data and verifying against out of sample data. Assuming finally we have identified parameter n of value 4 which gives a us 26.5% return from in sample data and 25% return from out of sample data. From this result it appears that the annual return from out of sample date has been significantly improved from the benchmark. We could conclude that we have found a optimum value for parameter n which most likely will work well too in live trading.
The following is the summary process of back testing
Implementing your strategy as code(custom formula) in Amibroker is not complicated but how could we verify that our strategy is actually working and profitable? The answer is you have to test your strategy against historical data. There are many providers which you can get KLSE end of day (EOD) historical data from. You should make sure the data is adjusted for bonus, split, consolidate and special large dividend.
The process of testing your strategy against historical data is called back testing. From the testing you could fine tune your code and parameters to improve the performance of the system. This is called optimization. However, over optimization will cause your system to only perform well on the data which you have tested against with. This is because the data is static and you optimize your code to fit the data. This issue is called curve fitting. Most probably in live trading, your system will not perform well as the result from your back testing. The solve this issue I will split my data to in sample data and out of sample data. The concept is simple, you do the back testing optimization against one set of data (in sample data) and then verify the performance of your system by testing against another set of data (out of sample data). You have done the right optimization if the performance of your system is consistent for in sample and out of sample data. The process of optimizing your system against in sample data and verify its result against out of sample data is also known as walk forward analysis. Amibroker support optimization and walk forward analysis out of the box.
Now I will use my strategy to explain about the back testing process above so that you could have better idea. Assuming you have implemented the volume spike strategy as I outlined in previous post and you have 20 years historical EOD data imported to Amibroker. Let us refer back to the setup of volume spike strategy, in the step to identify volume spike, we have parameter n as how many time the spike volume is greater than average volume. Assuming we set this parameter to 1.5 initially. Before back testing, we split our historical EOD as below:
- In sample - EOD from 1/1/1995 to 31/12/2004
- Out of sample - EOD from 1/1/2005 to 31/12/2014
Note that this is just a simplified example to explain the concept, in real back testing, we could split EOD to multiple sets of in sample and out of sample data.
Now, we can start testing our system against in sample data. Let us assume we only focus on annual return for now as performance indicator of your trading system (I will explain later about what aspects we should look at to determine the performance of a system in my next post, apparently, annual return should not be the only consideration). After back testing, we found that the annual return is 15% which we are not happy with. We should do another back test against out of sample data as a benchmark too, assuming that the annual return which we get is consistent which is also around 15%.
Now we will try to optimize this parameter by trying different value, let us say when we set this value to 5 and we notice that the back test result has been improved to 25% which meets our expectation. Then, we will need to verify our optimization result against out of sample data. For instance, the annual profit from back test against out of sample data is 16%. Obviously, the result is far behind our expectation, hence we haven't identified the optimum parameter. We should go back to optimized the parameter again and repeat the step of optimizing against in sample data and verifying against out of sample data. Assuming finally we have identified parameter n of value 4 which gives a us 26.5% return from in sample data and 25% return from out of sample data. From this result it appears that the annual return from out of sample date has been significantly improved from the benchmark. We could conclude that we have found a optimum value for parameter n which most likely will work well too in live trading.
The following is the summary process of back testing
Wednesday, April 8, 2015
Share Trading System Development - Volume Spike Strategy
Develop Share Trading System
At the end of my first post about systematic trading, I have posted the result of one of my trading system. I will re-post and explain about how to examine the result later. Finally, I will start writing about the strategy, high level development process and other details of the trading system which my audiences long awaiting for. Although I will touch some of the technical terms and development processes but this post (and generally this blog) is intended for any experienced traders without any programming experience who are interested to know more about system trading. So don't worry if you are not interested in developing your own system or you are not programmer, I will try to be concise and less emphasize on technical in this post. I believe it should make sense for any experience traders. However, if you are really interested in developing your own system, I don't think the information I provide here is enough for you to start. Please feel free to leave a comment or contact me so that I could provide more details and help you to start.
I call this strategy volume spike strategy. We know that share market is supply and demand market, more demand than supply will drive up the price.
Volume is a good indicator about demand of a share. In this strategy I will focus on volume increased which indicates that demand is pouring in to a share and also the share is getting notice by investors. Usually, a sudden volume increased also indicates that institutional investors are buying.
Ok, let me go straight to the point and show you the setup of this strategy. The setup and rules below have been implemented as custom formula in Amibroker except placing the buy/sell orders.
The Setup
Entry Rules
Exit Rules
In next post, I will explain about one of the most interesting and challenging process in trading system development - how to back test the strategy.
At the end of my first post about systematic trading, I have posted the result of one of my trading system. I will re-post and explain about how to examine the result later. Finally, I will start writing about the strategy, high level development process and other details of the trading system which my audiences long awaiting for. Although I will touch some of the technical terms and development processes but this post (and generally this blog) is intended for any experienced traders without any programming experience who are interested to know more about system trading. So don't worry if you are not interested in developing your own system or you are not programmer, I will try to be concise and less emphasize on technical in this post. I believe it should make sense for any experience traders. However, if you are really interested in developing your own system, I don't think the information I provide here is enough for you to start. Please feel free to leave a comment or contact me so that I could provide more details and help you to start.
I call this strategy volume spike strategy. We know that share market is supply and demand market, more demand than supply will drive up the price.
Volume is a good indicator about demand of a share. In this strategy I will focus on volume increased which indicates that demand is pouring in to a share and also the share is getting notice by investors. Usually, a sudden volume increased also indicates that institutional investors are buying.
Ok, let me go straight to the point and show you the setup of this strategy. The setup and rules below have been implemented as custom formula in Amibroker except placing the buy/sell orders.
The Setup
- Select shares which are in uptrend
- short term moving average of close price (close) is greater than long term moving average of close price
- Example: 10 days moving average of close is greater than 200 days moving average of close
- Identify volume spike
- volume is greater than n times of moving average of volume - n is a parameter
- spike volume is greater than m - m is a parameter
- price is up when volume spike
- After pullback(consolidation), generate buy signal
- the following are the conditions of pullback
- close is lower than previous close
- close shouldn't be lower than short term moving average of close
Entry Rules
- After receiving buy signal, on next day, check the stock price at around 10 minutes before market close, buy at market price if price is up from previous close, but only up for less than 10% (turn green)
Exit Rules
- Generate sell signal based on the following conditions
- 10% trailing stop from highest close since buying OR
- 10% initial stop loss from high of the buy day OR
- Close price drops below short term moving average
- Sell on next day open after receiving sell signal
In next post, I will explain about one of the most interesting and challenging process in trading system development - how to back test the strategy.
Tuesday, April 7, 2015
The life of a system trader
Before posting about the strategy of the result of system in my previous post, I will write a short post today to share what I do everyday in term of following my system, so you can have a glance what do you expect if you do the same.
The following are my daily routine:
What I need to remind myself is - since I am following a system I should follow it strictly and shouldn't override the decision of a system. So regardless of market condition, the price movement of the shares or the system is losing money (it is called system drawdown, I will touch about this concept in my next posts), I will still stick to the buy/sell signal of the system.
The following are my daily routine:
- Download KLSE EOD data from provider and import to Amibroker few hours after trading session ended, it takes me 2 minutes.
- Run my system to scan for buy/sell signal, it takes me 2 minutes.
- If I receive buy/sell signals I will buy/sell on the next day at market open/close (depends on the strategy of my system, I might need to buy only if the stock up - turn green), it probably takes me 5 minutes.
What I need to remind myself is - since I am following a system I should follow it strictly and shouldn't override the decision of a system. So regardless of market condition, the price movement of the shares or the system is losing money (it is called system drawdown, I will touch about this concept in my next posts), I will still stick to the buy/sell signal of the system.
Subscribe to:
Posts (Atom)